11,000 Homes a Day: Somebody Is Selling Them Why Not You?

11,000 Homes a Day: Somebody Is Selling Them Why Not You?

If you've been watching mortgage rates lately, you probably feel like you're watching a roller coaster. Rates that were around 6.3% this spring have moved back above 7%, and HousingWire is reporting significant day-to-day volatility as the bond market reacts to everything from inflation to geopolitical uncertainty. But here's what I think Realtors need to remember: people don't stop living their lives because mortgage rates move. We've been here before. Mortgage rates crossed 7% during 2024, and that year still produced 4.06 million existing-home sales in the United States. Do the math and that's roughly 11,100 homes sold every single day. And 2024 was actually the slowest year for existing-home sales since 1995! Think about that for a second. Even in one of the slowest housing markets in nearly three decades, more than 11,000 existing homes were still changing hands every day. The business didn't disappear. The question was and still is which agents found it?

That's why I think Realtors need to stop building their entire business plan around predicting the next mortgage-rate move. Yes, we'd all love to see rates back in the 5s. Maybe they'll get there and maybe they won't. But sitting around waiting for the "perfect" interest rate isn't a business strategy. Instead, start looking for the people whose lives are telling them it's time to move. People get married. Couples get divorced. Babies are born. Families outgrow homes. Children leave for college. Parents downsize. People get transferred. Companies relocate employees. People inherit property. Renters decide they're ready to own. Retirees move closer to their children. None of those life events checks the 10-year Treasury before happening. A family expecting its third child may not be able to wait two years for the perfect mortgage rate because their two-bedroom condo isn't getting any bigger.

And nowhere is that more relevant than here in South Florida. Miami-Dade, Broward and Palm Beach aren't markets driven by just one type of buyer. We have local families moving up and down, retirees, international buyers, professionals relocating for work, people moving here from other states, newly married couples buying their first home and longtime owners deciding that their current home no longer fits their lives. That diversity is one of South Florida real estate's greatest strengths. The opportunity for Realtors is to stop asking "Who wants to buy at today's rate?" and start asking "Who needs to make a housing decision this year?" Those are two very different questions. The first one leads you toward people sitting on the sidelines watching CNBC. The second leads you toward actual transactions.

And today's market can give those buyers something the frenzy market couldn't: options and negotiating power. Higher rates are certainly a challenge for affordability—there's no point pretending otherwise. Freddie Mac's September 24 average for a 30-year fixed mortgage was 7.03%, compared with rates in the low-to-mid 6% range earlier this year. But rates are only one part of a transaction. Depending on the property and submarket, today's buyer may be able to negotiate price, seller concessions, closing costs or a rate buydown in ways that were extremely difficult when multiple offers were flying around. So our job as Realtors isn't to convince someone who has no reason to move that they suddenly need a house. Our job is to find the people who already have a reason to move and help them figure out how to make the numbers work. That's where good agents, creative lenders and smart negotiation become incredibly valuable.

So here's my challenge to South Florida Realtors this fall: stop waiting for the market to give you permission to succeed. Four million existing homes sold in America in 2024 despite elevated mortgage rates. Behind every one of those transactions was a reason marriage, divorce, a new baby, a new job, retirement, relocation, financial change or simply a family deciding it was time for something different. Those life events are happening right now in Miami, Coral Gables, Doral, Weston, Aventura, Fort Lauderdale, Boca Raton and communities throughout South Florida. Find those people. Talk to them. Educate them. Help them understand their options. The market doesn't have to be perfect for you to have a great market. And if you see today's market differently, I genuinely want to hear it. Reach out, let's connect and let's have the conversation because the best Realtors don't just talk about where the market has been; we're constantly learning from each other about where it's going next.
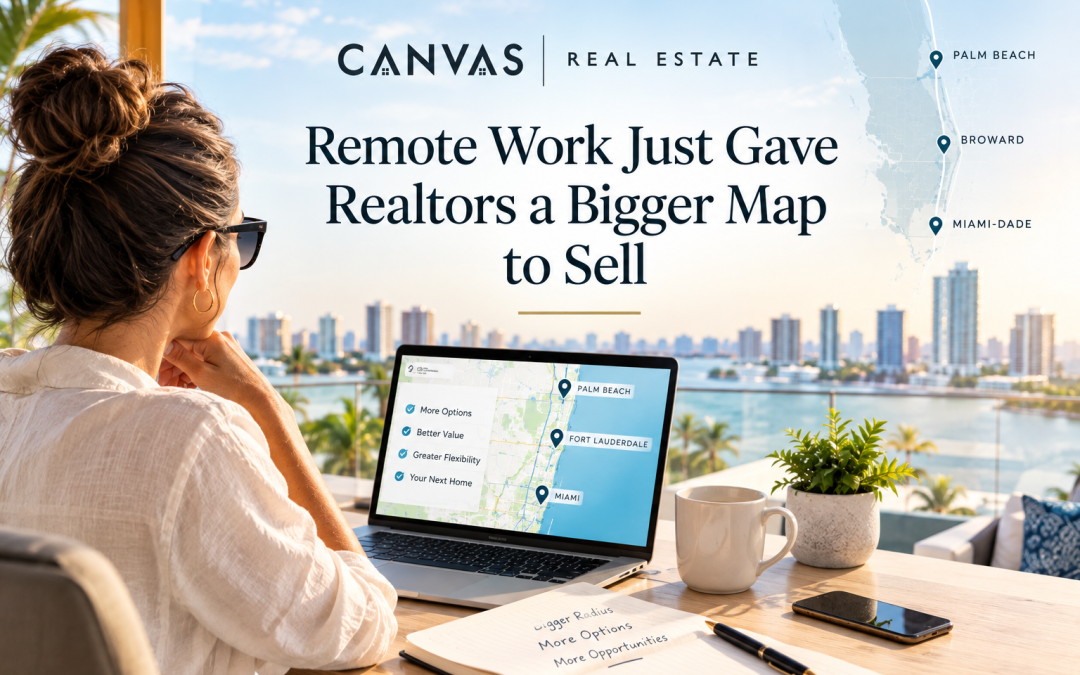
Remote Work Just Gave Realtors a Bigger Map to Sell

Remote Work Just Gave Realtors a Bigger Map to Sell

For Realtors, the remote-work conversation should not be about whether people are going back to the office. It should be about what flexibility does to a buyer’s search radius. Keeping Current Matters recently reported that remote job postings increased 22% quarter over quarter, marking the second consecutive quarter of double-digit growth. That matters because a buyer who only needs to be in an office once or twice a week does not have to shop for a home the same way someone commuting five days a week does. And in South Florida, where pricing can change dramatically from one neighborhood, city, or county to another, that creates an opportunity for Realtors to solve one of the biggest problems buyers face today: affordability.

The first thing Realtors should do is change the questions they ask during the buyer consultation. Instead of only asking, “Where do you work?” ask, “How often do you actually have to be there?” That one question could completely change the search. A buyer employed in Brickell who works remotely three or four days a week may not need to live within a few miles of Brickell. Someone working in Fort Lauderdale may be able to consider communities farther west, north, or south. A buyer originally focused on Miami-Dade may suddenly be open to Broward, and someone working in Broward may be able to expand into Palm Beach. Your job is no longer simply to search the zip codes the buyer gives you. Your job is to show them what happens to their purchasing power when you expand the map.

That is also how Realtors can turn an affordability objection into a conversation instead of a dead lead. When a buyer says, “I can’t afford what I want,” don't immediately assume they need to reduce their expectations or wait another year. Show them alternatives. Compare what their budget buys 10, 20, or 30 miles away. Show them the difference in square footage, bedrooms, yards, amenities, schools, lifestyle, and property type. A buyer who cannot get the three-bedroom home and office they want near a major employment center may discover that the same budget works somewhere else in the region. And if that person only drives to work once or twice a week, an additional 20 or 30 minutes on those commuting days may be a very reasonable exchange for a home that works better the other five days of the week.

Realtors should also be using this information to prospect. Go back through your database and identify buyers who stopped looking because of price. Call the people who told you six months ago that they could not find enough house for their budget. Talk to renters whose leases are coming up. Create social media content showing “What $600,000 buys here versus 25 miles away.” Run side-by-side comparisons of communities. At open houses, ask visitors whether their jobs are remote or hybrid. If they tell you they only commute twice a week, you may immediately have the opportunity to introduce them to communities they have never considered. Remote work gives good Realtors something incredibly valuable: another solution to present when price, inventory, or location appears to be stopping the transaction.

And that may be the biggest lesson for Realtors in today's market. We cannot sit around waiting for rates to fall dramatically, inventory to become perfect, or buyers suddenly to have bigger budgets. Our value is finding solutions with the market we have today. Remote and hybrid work have changed the relationship between employment and housing, and Realtors who understand that can help buyers see South Florida differently. Miami-Dade, Broward, and Palm Beach should not always be treated as isolated markets; for a flexible worker, they can become one much larger search area filled with different price points and lifestyles. The Realtor who simply sends listings is competing with an app. The Realtor who can take a buyer who believes they cannot afford a home, expand their options, and show them a path to ownership is providing real value. That is how information becomes opportunityand how great Realtors create transactions that otherwise would never have happened.

Florida Retirement Is Getting Younger .  And South Florida Real Estate Should Pay Attention

Florida Retirement Is Getting Younger .  And South Florida Real Estate Should Pay Attention

Florida has always been synonymous with retirement, but I believe the more important story today is who is retiring here   and when they are coming. WalletHub just ranked the three best retirement cities in America, and all three are in Florida: Orlando No. 1, Miami No. 2 and Tampa No. 3. Miami's appeal goes well beyond sunshine. WalletHub compared 182 cities across 45 measures covering affordability, activities, quality of life and healthcare, and Miami ranked especially well because of its extraordinary combination of recreation, culture, walkability, transportation, healthcare access and Florida's tax environment. Miami ranks first nationally for adult volunteer opportunities, art galleries and fishing facilities per capita, is the sixth-most walkable city in the study and benefits from Florida having no individual state income tax and no estate or inheritance tax. It also ranks No. 1 for home healthcare facilities per capita, No. 18 for the cost of homemaker services and No. 21 for geriatric hospitals. 

But dig beneath the word “retiree” and the story gets much more interesting for South Florida real estate. Florida Realtors economists found that households ages 55 to 64 generated $7.6 billion in net household-income inflow into Florida in 2023–2024  more than any other age group. Their conclusion is particularly important: many of these households are moving to Florida before they retire, while they're still working and often near their peak earning years. Florida was also the only state to rank in the top 10 for net migration among Baby Boomers, Gen X, Millennials and Gen Z in U-Haul's July 2025-to-June 2026 data; Florida ranked No. 1 for both Gen X and Millennials and No. 3 for Baby Boomers. That tells me we aren't simply seeing retirement migration. We're seeing people deliberately moving their lives to Florida earlier. (Florida Realtors)

And South Florida provides perhaps the clearest evidence of this new demographic. SmartAsset found that 17.45% of Pembroke Pines' population is between 55 and 64  the highest percentage among the cities it studied, representing nearly 30,000 people approaching traditional retirement age. Households ages 45–64 there had a median income of $111,528, and 20% earned more than $200,000. At the national housing-market level, the same shift is visible: Baby Boomers now represent 42% of all home buyers, more than any other generation, and NAR's 2026 data shows the younger boomer group, ages 61–70, accounts for 27% of recent buyers, compared with 15% for older boomers ages 71–79. These are not necessarily buyers looking for yesterday's definition of a retirement community. Many are active, financially established consumers looking for lifestyle, convenience, culture, restaurants, recreation, family proximity and the ability to keep working if they choose. (SmartAsset)

That distinction could have enormous implications for South Florida housing. A 60-year-old relocating today may have a very different real estate journey than an 80-year-old retiree. They may sell a high-equity home in another state, purchase a primary residence here, continue working remotely or operating a business, eventually buy an investment property, help an adult child purchase a home and then make another housing move later in retirement. They also bring considerable purchasing power. NAR reports that 39% of buyers ages 61–70 paid cash, compared with just 26% of buyers overall, while decades of accumulated home equity have made boomers unusually mobile in today's higher-rate environment. This is why I believe South Florida's retirement advantage should be viewed not simply as a senior-housing story, but as a long-duration real estate opportunity involving relocation, luxury, downsizing, second homes, investment property and multigenerational housing. (Florida Realtors)

For Realtors, this changing demographic requires a different level of expertise. These consumers may arrive with substantial equity and sophisticated expectations, and they're often making decisions involving taxes, lifestyle, financing, investments, family and long-term planning at the same time. They don't simply need someone to open a door; they need someone who understands the differences between Miami-Dade, Broward and Palm Beach, can explain communities and property types, understands relocation and can connect today's purchase to the client's longer-term objectives. And despite all of the technology available to consumers, professional representation remains extraordinarily important: NAR's 2026 research found 88% of buyers purchased through a real estate agent and 91% of sellers used one. The opportunity isn't disappearing  but the level of Realtor required to capture it is rising. (NAR)

That is exactly where I see the opportunity for CANVAS Real Estate and the agents who choose to build their careers with us. The future of South Florida real estate isn't one-dimensional: it is younger retirees arriving earlier, equity-rich boomers making lifestyle moves, Gen X households relocating during their highest-earning years, international buyers, investors and younger generations following them. The brokerage of the future has to prepare agents to understand all of those customers instead of waiting for yesterday's market to return. At CANVAS, that is the future we should be building toward agents who understand data, demographics, relocation, investment and the entire South Florida marketplace. Florida may have been America's retirement destination for generations, but the next wave is arriving younger, wealthier and with more years of real estate decisions ahead of them. For Realtors who recognize that shift, the opportunity may be just beginning and CANVAS Real Estate intends to be part of what comes next.

South Florida’s Next Real Estate Boom Is Already Taking Shape

South Florida’s Next Real Estate Boom Is Already Taking Shape

South Florida’s next great real estate story may already be unfolding in front of us. For years, Miami has been the region’s global calling card, attracting capital, businesses, investors and new residents from around the world. But the newest wave of development suggests the opportunity is expanding far beyond Miami’s city limits. Today, nearly half of Fort Lauderdale’s current downtown development footprint approximately 4.6 million square feet is associated with New York firms. Compare that with 2021 through 2024, when New York developers represented only about 13% of completed projects in Fort Lauderdale. That kind of acceleration is not simply a development story. It is a powerful vote of confidence in the future of South Florida.

Follow the capital and the picture becomes even clearer. Developers are committing enormous sums to luxury condominiums, rental towers and mixed-use communities that will not even be delivered for several years. The planned Ombelle development will bring 754 units in two towers, with completion anticipated around 2028, and one of those towers is already 45% presold. The project is also expected to include Fort Lauderdale’s first Equinox gym. Elsewhere, developer Miki Naftali is pursuing more than 250 condominiums plus a rental building in Flagler Village, while Cain and Kushner recently proposed another 440 residential units in Fort Lauderdale. Nearby Dania Beach has a proposed $350 million office development featuring two 10-story towers. These developers are not investing based on what South Florida looked like yesterday. They are investing based on what they believe it will become tomorrow.

The demographic story may be even more compelling. More than 125,000 New Yorkers relocated to Florida between 2018 and 2022, bringing nearly $14 billion in adjusted gross income with them. Approximately 41,250 of those New Yorkers settled in Miami-Dade, Broward and Palm Beach counties. South Florida is not simply gaining residents; it is gaining income, businesses, purchasing power, entrepreneurship and investment capital. At the same time, the number of adults under age 45 living in downtown Fort Lauderdale has increased 25% since 2020. This is not simply the traditional Florida story of retirees moving south. We are attracting working professionals, executives, business owners and younger families who may remain here for decades and each new household creates opportunities across residential sales, rentals, investment properties and commercial real estate.

What is happening in Fort Lauderdale should not be viewed as competition with Miami. It should be viewed as the expansion of Miami’s success throughout the region. Fort Lauderdale’s median home price remains approximately $70,000 below Miami, although that gap was approximately $120,000 only a year ago. Meanwhile, Brightline connects downtown Fort Lauderdale and downtown Miami in approximately 40 minutes, making the region more connected than ever. Miami-Dade, Broward and Palm Beach are increasingly functioning less like three isolated markets and more like one enormous South Florida economic corridor. Buyers can live in one county, work in another and enjoy the lifestyle of all three. Developers understand that. Investors understand it. And the real estate professionals who recognize it early will be positioned to participate in opportunities across the entire region.

This is also why today's Realtor has to think differently. Interest rates will rise and fall. Inventory will expand and contract. Monthly sales reports will fluctuate. But demographic shifts, billions of dollars in incoming wealth, millions of square feet of new development and massive infrastructure investment represent longer-term forces. South Florida’s largest condo developers closed on more than 2,000 units during the first half of 2026 alone, demonstrating that meaningful transaction activity continues even while headlines focus on short-term market uncertainty. The agents who thrive over the next decade will not simply wait for easier market conditions. They will understand development, investment, migration, financing, new construction and the increasingly interconnected nature of South Florida and they will align themselves with a brokerage that sees the same future.

That is exactly the opportunity we are building at CANVAS Real Estate. We believe the future belongs to agents who see themselves as more than people who open doors and write contracts. They are advisers, marketers, negotiators and entrepreneurs operating in one of the most dynamic real estate regions in America. As Miami’s global influence spreads north through Broward and Palm Beach, CANVAS is focused on giving agents the education, technology, leadership and platform to grow with it. South Florida’s next chapter is already being written, and the question for Realtors is not whether opportunity is coming it is whether they are positioned to capture it. If you believe the future of real estate is being built right here in South Florida, maybe it is time to build your future with CANVAS Real Estate.

Inflation Is Eating Your Cash. That’s Exactly Why Real Estate Matters.

Inflation Is Eating Your Cash. That’s Exactly Why Real Estate Matters.

Here’s the housing headline nobody wants to write: inflation may be bad for your grocery bill, but it can be very good for the long-term case for owning real estate. August inflation came in hotter than expected, with consumer prices rising 0.4% in one month and 3.4% from a year ago. Shelter costs climbed another 0.3% for the month and 3% year-over-year, while the average 30-year mortgage moved up to 6.76% ahead of the Federal Reserve’s September 16 decision. The immediate reaction is predictable: inflation is bad, rates could stay higher, and housing affordability gets tougher. All true. But investors should ask a different question: if the dollar is buying less every year, what happens to the value of assets that cannot simply be printed? Real estate is land, labor, lumber, concrete and infrastructure. Inflation doesn't just raise the cost of living it raises the cost of creating the next house. 

And the replacement-cost story may be one of the most overlooked forces supporting real estate values today. Residential building-material prices excluding energy were already 5% higher year-over-year in July, the fastest annual increase since late 2022, while builders themselves reported a median 6.7% increase in material costs for constructing the same house. Softwood lumber alone was up 17.3% from a year earlier.  Think about that for a moment. If the land costs more, materials cost more, labor costs more, insurance costs more and financing costs more, how exactly are we supposed to magically produce dramatically cheaper housing? Inflation raises the replacement cost of real estate, and eventually the value of existing real estate has to compete with what it costs to build the next property. That doesn't mean every house appreciates every year. It means inflation can create a powerful structural argument for owning an asset whose supply is expensive to reproduce.

Then comes one of real estate's most misunderstood advantages: leverage. If you buy a property with long-term fixed-rate debt, your mortgage balance does not rise every time inflation rises. The Federal Reserve Bank of St. Louis has explained that inflation reduces the real value of nominal liabilities—including fixed mortgage debt—because those obligations are eventually repaid with dollars that have less purchasing power. Imagine borrowing $400,000 today and controlling a $1,000,000 asset. Twenty years from now, the mortgage is still based on the dollars you borrowed today, while wages, rents and property values may be dramatically different. That is the power of intelligently using someone else's money to control a hard asset while inflation slowly attacks the real value of the debt. Cash loses purchasing power. Properly structured fixed debt can do exactly the opposite for the borrower.

And real estate has something many inflation hedges do not: it can produce income while you own it. National asking rents reached $1,962 in July, up 2.3% year-over-year, the fastest annual growth in more than a year. In Miami, typical rents were roughly $2,677 and up 1.4% annually in Zillow's July data. That doesn't mean every rental is a great investment or that rents always rise faster than expenses South Florida investors especially must account for taxes, insurance, condo fees, maintenance and reserves. But look at the structure: an investor can own an appreciating physical asset, potentially finance much of it with fixed debt, collect income from someone using it and potentially increase that income over time. That is why sophisticated investors don't look at real estate merely as four walls and a roof. They look at an income-producing balance-sheet asset.

Of course, inflation has a dark side for real estate too and pretending otherwise would be foolish. Persistent inflation can keep interest rates elevated, suppress affordability and temporarily slow transactions. Today's 6.76% mortgage rate is evidence of that pressure. Yet even with elevated borrowing costs, FHFA reports U.S. home values were still 2.1% higher year-over-year in the second quarter of 2026, with prices appreciating in 46 states plus Washington, D.C. Even more remarkable, the United States has now recorded positive annual home-price appreciation in every quarter since the beginning of 2012. Investors also haven't disappeared: they represented about 19% of U.S. home purchases in the first quarter, even as higher costs made them more selective. The lesson isn't “buy anything because inflation is coming.” The lesson is that periods of uncertainty often separate investors who understand value from consumers who only understand price.

That shift should be a wake-up call for Realtors, because the next wave of this business may be much bigger than simply helping someone find their primary residence. At CANVAS Real Estate, we believe the next generation of top agents needs to understand real estate as an investment class as well as shelter. That means learning cash flow, cap rates, leverage, DSCR financing, equity, appreciation, rental strategy, new construction, multifamily, tax considerations and how inflation changes the economics of ownership. A client who buys one house to live in may complete a transaction every seven or ten years. A client who learns how real estate can become part of a wealth-building strategy may buy again and again and refer other investors who do the same. The future Realtor isn't simply opening doors. The future Realtor understands what the asset behind that door can do.

So maybe inflation isn't simply the enemy everyone keeps telling us it is. Maybe it is also the flashing billboard reminding us why ownership matters. When dollars lose purchasing power, scarce assets matter more. When construction becomes more expensive, existing real estate becomes harder to replace. When rents increase, income-producing property becomes more interesting. And when fixed debt is repaid over decades with future dollars, leverage becomes a wealth-building tool instead of merely a mortgage payment. The next real estate wave may not be defined by Americans simply asking, “Where should I live?” It may be defined by millions asking, “What should I own?” At CANVAS Real Estate, we intend to coach and develop the agents who are ready for that conversation—the entrepreneurial Realtors who recognize that real estate isn't just shelter. It's an asset class. And the agents who understand that distinction may be the ones who ride the next wave instead of watching it pass them by.

The American Dream Isn’t Dead. The Old Playbook Is.

The American Dream Isn’t Dead. The Old Playbook Is.

Can we please stop declaring the American Dream dead every time housing gets expensive? The latest Entrata survey says 71% of renters believe the American Dream is changing, more than 80% say renting is the smarter financial decision for them right now, and 47% say homeownership feels unaffordable. Those numbers are already being used to write the obituary for homeownership. There’s just one problem: 61% of those same renters still say owning a home is part of their personal American Dream. The dream isn’t dead. The old rulebook is.

For decades we sold Americans one version of success: save 20%, get married, buy a three-bedroom single-family home in the suburbs, take out a 30-year mortgage and stay there forever. That version of the American Dream is increasingly obsolete. Today’s buyers are buying condos first. They’re buying townhomes. They’re purchasing with siblings, parents and partners. They’re creating multigenerational households. They’re house hacking. They’re using down-payment assistance, seller concessions, rate buydowns and builder incentives. They’re buying the property they can afford today instead of waiting forever for the property Instagram told them they deserve. That isn’t failure. That’s strategy.

And here’s the part the doom-and-gloom housing crowd keeps missing: “I can’t afford the traditional path” does not mean “I can’t build wealth through real estate.” Nearly 40% of renters surveyed said the combination of monthly mortgage payments and upfront costs is currently beyond their reach. Fair enough. Affordability is real. But smart buyers aren’t waiting around for mortgage rates to magically return to 3%, prices to collapse and their salaries to double at exactly the same time. They are changing the equation. Maybe the first property has two bedrooms instead of four. Maybe it’s farther west. Maybe the garage becomes less important than the monthly payment. Maybe you rent out a room. Maybe you buy something imperfect and let time, equity and income help you move up later.

Gen Z may understand this better than anyone. A remarkable 81% of Gen Z renters now say renting is the smarter financial decision for their household, up from 72% just one year ago. Some people look at that statistic and see a generation giving up. I see a generation doing the math. They’re questioning assumptions their parents never questioned. They want mobility. They want financial flexibility. They don't necessarily want to become house-poor just so they can say they own something. Good. The next generation of homeowners may actually be smarter because they refuse to blindly follow the last generation’s formula.

Even the definition of success is shifting. Seventy-five percent of renters say financial stability now feels more like the American Dream than simply owning a home, while more than 60% value the ability to relocate easily over the stability associated with ownership. Why are we treating those ideas as enemies? Financial stability should be the goal. Real estate is one tool for getting there. Sometimes the smart move is to rent today and buy next year. Sometimes it’s buying a starter condo instead of waiting seven years for your “forever home.” Sometimes it’s purchasing an investment property before the dream house. The American Dream was never supposed to be about impressing your neighbors. It was supposed to be about creating opportunity for yourself and your family.

This changing landscape is also exposing a huge weakness in our own industry. If your only advice to a buyer is “wait until rates come down,” you’re not advising you’re spectating. At CANVAS Real Estate, we coach agents to succeed in the market that exists, not the market they wish existed. That means understanding financing, concessions, first-time-buyer programs, new-construction incentives, creative ownership strategies, investment opportunities and hyperlocal market conditions. A Realtor’s value today isn't opening a lockbox. It is helping a consumer see a path they couldn't see on their own. Anyone can sell real estate when everything is easy. Great agents are created when it isn’t.

So no, the American Dream is not dead. It got an upgrade. It may start with a condo. It may include roommates. It may involve family members pooling resources. It may mean buying smaller, farther away or earlier than you expected. It may involve renting first, investing second and buying your dream home third. The winners in this housing market will not be the people waiting for 2019 to come back. They will be the buyers willing to adapt and the Realtors sophisticated enough to show them how. At CANVAS Real Estate, that is exactly the agent we are building: educated, entrepreneurial and prepared to win in every market.